Tax rules
Single-Shareholder S Corporation Payroll Governance: The Watertight Tax, Compensation, and Compliance Playbook for Solopreneurs
Updated · clark056
Affiliate disclosure: Payroll Research may earn a commission if you sign up through links on this page. It never changes our price math or rankings.
Quick answer: A one-owner S corporation saves money only if its payroll can survive an IRS review. That means a documented, market-based salary run on a regular schedule, health insurance coded correctly on your W-2, business expenses reimbursed under a written accountable plan, and a salary level chosen with the Section 199A deduction and your retirement contributions in mind. Get one piece wrong and the IRS can reclassify your distributions as wages, with back payroll taxes, penalties and interest for every open year.
This is the advanced companion to our plain-English guide, S-Corp Payroll Rules for a Single-Member Owner. If you’re still deciding whether to elect S-corp status, start there. If you’ve elected and want your setup to hold up, keep reading.
Introduction: the solo owner plays two legal roles
When a single-member LLC or corporation elects S-corporation status, the owner takes on two legal identities at once:
- Shareholder: the 100% equity owner, entitled to the company’s profits as distributions.
- Employee: under IRC §3121(d)(1), any officer of a corporation is an employee for federal employment tax purposes. IRS Fact Sheet 2008-25 applies this directly to S-corporation officers who perform more than minor services.
The tax incentive comes from the gap between those two roles. Wages carry Social Security and Medicare tax (15.3% combined, split between employer and employee, with the 12.4% Social Security portion stopping at the 2026 wage base of $184,500). S-corporation distributions do not carry FICA tax. Business profit still passes through to your personal return either way, but only the wage portion is hit with payroll tax.
That gap is exactly why the IRS scrutinizes one-owner S corps. A zero salary, or a token salary next to large distributions, is the pattern behind most of the case law below. The goal of payroll governance is a salary and a paper trail that a revenue agent would accept on the first read.
Section 1: Reasonable compensation you can defend
The 60/40 rule has no legal authority
You’ll often hear that a safe split is 60% salary and 40% distributions, or some other fixed ratio. No statute, regulation, revenue ruling or court decision adopts any percentage. Courts set reasonable compensation from facts about the owner and the business, and the IRS’s own guidance says the Code and regulations “provide no specific guidelines.” A ratio can be too high for a capital-heavy business and far too low for a one-person consulting firm whose profit comes almost entirely from the owner’s labor.
The IRS’s nine factors
IRS Fact Sheet FS-2008-25, Wage Compensation for S Corporation Officers, lists the factors courts have used. Build your salary file around them:
| Factor | What to document |
|---|---|
| Training and experience | Degrees, licenses, certifications and years in the field |
| Duties and responsibilities | Every role you perform: delivery, sales, admin, management |
| Time and effort devoted to the business | Typical weekly hours; full-time vs part-time |
| Dividend history | Distributions taken in prior years relative to salary |
| Payments to non-shareholder employees | What you pay staff or contractors for comparable work |
| Timing and manner of paying bonuses | Whether bonuses follow a policy or appear at year-end |
| What comparable businesses pay | Market wage data for the roles you fill |
| Compensation agreements | Any written salary resolution or employment agreement |
| Use of a formula to determine compensation | The method behind the number, applied consistently |
The cases that set the boundaries
| Case | Facts | Holding / lesson |
|---|---|---|
| Joseph Radtke, S.C. v. United States (7th Cir. 1990) | Sole shareholder attorney took no salary; all payments were labeled dividends | Payments for his legal services were wages. A zero salary with dividends does not work. |
| Spicer Accounting, Inc. v. United States (9th Cir. 1990) | Accountant-owner took distributions instead of wages for his services | An officer who provides substantial services is an employee under §3121(d); the payments were wages. |
| JD & Associates, Ltd. v. United States (D.N.D. 2006) | Sole-shareholder CPA firm; the IRS challenged distributions as disguised wages | The court reclassified part of the distributions as wages after weighing the owner’s experience, comparable pay and the firm’s results. |
| David E. Watson, P.C. v. United States (8th Cir. 2012) | Experienced CPA paid himself $24,000 a year while taking distributions of $203,651 (2002) and $175,470 (2003) | Reasonable salary set at $91,044 based on a valuation expert’s analysis; the extra $67,044 a year became subject to FICA. |
The pattern across these cases: the more your profit comes from your own professional work, and the more experienced you are, the harder it is to defend a low salary. In Watson, a firm grossing over $2 million a year and an owner with decades of experience made $24,000 look indefensible.
What reclassification costs
If the IRS treats part of your distributions as wages, the corporation owes the unpaid employment taxes for each affected quarter, and the bill compounds:
- Back FICA: both the employer and employee shares (15.3% up to the wage base), plus FUTA.
- Failure to deposit (IRC §6656): 2% if deposits are 1–5 days late, 5% for 6–15 days, 10% after 15 days, and 15% if still unpaid 10 days after an IRS notice.
- Failure to file or pay (IRC §6651): on Forms 941 that understated wages.
- Accuracy-related penalty (IRC §6662): up to 20% of an underpayment attributable to negligence or a substantial understatement, where it applies.
- Interest: runs on all of the above from each original due date, across every open year.
Compliance trap: Reclassification usually covers several years at once. A salary that’s $40,000 too low for three years can mean six figures of back taxes, penalties and interest, which is far more than the FICA you saved.
The multi-role cost method
Most solo owners do several jobs. A defensible way to price your salary is to blend market rates for each role in proportion to the time you spend on it, using Bureau of Labor Statistics Occupational Employment and Wage Statistics (OEWS) data for your area:
- List your roles in three tiers: direct technical services (the billable work), operations and administration (bookkeeping, scheduling, invoicing) and executive management (strategy, sales, hiring).
- Estimate the share of your working hours spent in each tier.
- Look up a market wage for each role, choosing the occupation code and percentile that match your experience.
- Multiply each wage by its time share and add them up.
| Role tier (example: software consultant) | Time share | Market wage (illustrative) | Weighted |
|---|---|---|---|
| Direct technical services: software developer | 70% | $130,000 | $91,000 |
| Operations and administration: bookkeeping clerk | 15% | $48,000 | $7,200 |
| Executive management: general manager | 15% | $110,000 | $16,500 |
| Blended reasonable salary | 100% | $114,700 |
The wages above are placeholders to show the math. Pull current OEWS figures for your metro area and occupation each year. Then adjust for part-time hours, and cap the salary at what the business can actually afford to pay.
Record the result in writing. For an LLC taxed as an S corp, that’s usually a written consent of the member; for a corporation, a board resolution. Attach the wage data, your time estimates and the calculation, and redo it each year.
Section 2: 2% shareholder health insurance and the Box 5 trap
Why your premiums are treated differently
IRC §1372 treats anyone owning more than 2% of an S corporation as a partner for fringe-benefit purposes. As a result, you lose the §106 exclusion that lets ordinary employees receive employer-paid health coverage tax-free. Instead, the premiums go through a three-step process set out in IRS Notice 2008-1.
The three-step process
- The S corporation pays or reimburses the premiums. The policy can be in the company’s name or yours, but if you pay personally, the company must reimburse you during the same year. If neither happens, the plan isn’t treated as established by the business.
- The premiums go on your W-2 as wages. They’re included in Box 1, but excluded from Box 3 (Social Security wages) and Box 5 (Medicare wages) under IRC §3121(a)(2)(B). Many payroll providers also show the amount in Box 14 for reference.
- You deduct the premiums on your personal return. Claim the self-employed health insurance deduction under IRC §162(l) on Form 7206, which flows to Schedule 1 of Form 1040.
| W-2 box | Correct treatment | Common mistake |
|---|---|---|
| Box 1: wages, tips, other compensation | Include the premiums | Leaving them out, which breaks the deduction |
| Box 3: Social Security wages | Exclude the premiums | Including them, which overpays FICA |
| Box 5: Medicare wages | Exclude the premiums | Including them, which overpays FICA |
| Box 14: other | Optional informational line (e.g. “2% S-corp health”) | Treating Box 14 as a substitute for Box 1 |
The Box 5 trap
The deduction can’t exceed your earned income from the business that established the plan (IRC §162(l)(2)(A)). For a 2% shareholder, §162(l)(5) defines that earned income as your wages from the S corporation as defined in §3121, which in practice means your Box 5 Medicare wages, not Box 1.
Compliance trap: If you pay yourself no salary and run only your health premiums through payroll, Box 1 shows the premiums but Box 5 is $0. The earned-income limit is then $0, so the entire deduction is disallowed, and you pay income tax on premiums that sit in Box 1 with nothing to offset them. Any real salary large enough to cover the premiums fixes this.
Two timing rules matter here. Add the premiums to your W-2 before the year’s final payroll run, not after the W-2 has been issued. And if you’re eligible for subsidized coverage through a spouse’s employer, you can’t take the deduction for those months.
Section 3: the accountable plan (Treas. Reg. §1.62-2)
As an employee of your own company, you’ll pay for some business costs personally: a home office, mileage, a phone. How the company pays you back determines how those payments are taxed.
Without a qualifying plan, a reimbursement counts as a non-accountable payment. It’s taxable W-2 wages, subject to income tax withholding and FICA. With an accountable plan, the same reimbursement is tax-free to you and still deductible by the company.
The three requirements
Under IRC §62(c) and Treas. Reg. §1.62-2, an accountable plan must meet all three:
- Business connection: the expense is an ordinary and necessary business expense (IRC §162) that you incurred as an employee of the company.
- Substantiation: you document the amount, date, place and business purpose. Under the regulations’ fixed-date safe harbor, substantiation within 60 days of the expense is treated as timely.
- Return of excess: any advance beyond what you substantiate is returned. Under the same safe harbor, returning it within 120 days is timely.
Expenses commonly reimbursed to solo owners
- Home office: the business-use share (by square footage) of rent or mortgage interest, utilities, repairs and homeowners or renters insurance. The space must be used regularly and exclusively for the business.
- Business mileage: at the IRS standard mileage rate for the year, backed by a contemporaneous log of dates, destinations, purposes and miles.
- Phone and internet: the business-use percentage of mixed-use services.
Formalities that make it hold up
- Adopt a written accountable plan by member consent or board resolution before you start reimbursing.
- Submit an expense report with receipts or logs for each reimbursement.
- Pay reimbursements as separate transfers, not mixed into payroll or owner draws, so each payment is traceable to an expense report.
| Accountable plan reimbursement | Non-accountable payment | Owner distribution | |
|---|---|---|---|
| What it is | Repayment of documented business expenses | Allowance or reimbursement without substantiation | Share of profit paid to you as owner |
| On your W-2? | No | Yes, as wages | No |
| Income tax to you | None | Yes | Profit is taxed on your return via the K-1 either way |
| FICA | None | Yes, 15.3% | None |
| Deductible to the company | Yes | Yes, as wages | No |
| Paperwork needed | Written plan, expense reports within 60 days | Payroll processing | Reduces stock basis; keep pro rata if owners are added |
Section 4: Section 199A (QBI) and 2026 salary planning
What changed for 2026
The One Big Beautiful Bill Act (OBBBA), signed in July 2025, made the 20% qualified business income deduction under §199A permanent. For tax years beginning after December 31, 2025, it also:
- Widened the phase-in ranges from $50,000 to $75,000 (single) and from $100,000 to $150,000 (married filing jointly).
- Added a $400 minimum deduction for taxpayers with at least $1,000 of QBI from active businesses they materially participate in, indexed for inflation after 2026.
For 2026, Rev. Proc. 2025-32 sets the thresholds at:
| Filing status | Phase-in starts | Phase-in ends |
|---|---|---|
| Single and other returns | $201,750 | $276,750 |
| Married filing jointly | $403,500 | $553,500 |
| Married filing separately | $201,775 | $276,775 |
These thresholds are measured against your taxable income before the QBI deduction, not your business profit.
The trade-off between FICA and QBI
Your own salary is a deductible wage expense to the S corporation, so it reduces the business’s QBI. Each extra $1 of salary lowers QBI by $1 (and by a bit more once you add the employer’s share of FICA), which costs you roughly $0.20 of deduction. How much that matters depends on where your taxable income lands:
- Below the threshold: no W-2 wage limit applies. The lowest defensible salary maximizes both QBI and FICA savings. Your reasonable-compensation analysis sets the floor.
- Above the phase-in range, non-SSTB: the deduction is capped at the greater of 50% of W-2 wages paid by the business, or 25% of W-2 wages plus 2.5% of the unadjusted basis of qualified property. Your own salary counts as W-2 wages, so a $0 salary means a $0 deduction for a business with no other employees or property.
- Specified service trades or businesses (SSTBs): consulting, law, accounting, health, financial services, performing arts and similar fields. Above the end of the phase-in range ($276,750 single / $553,500 joint), the deduction is zero no matter what salary you pay.
The 2/7 rule for high earners above the range
For a non-SSTB with no other employees and little property, the deduction is the smaller of 20% of QBI and 50% of wages. Let P be profit before your salary and W your salary (ignoring the employer’s FICA for simplicity):
- QBI = P − W, so the 20% amount is 0.20 × (P − W)
- The wage cap is 0.50 × W
- They’re equal when 0.20P = 0.70W, so W ≈ 28.6% of P (2/7)
For $400,000 of pre-salary profit, that’s a salary of about $114,300, which yields the largest QBI deduction (about $57,100). Above that, extra salary costs FICA and QBI; below it, the wage cap shrinks the deduction. If your reasonable-compensation study supports a higher number, the study wins.
Income tier decision matrix
| Taxable income (2026) | Non-SSTB (e.g. e-commerce, agency, construction) | SSTB (e.g. consulting, accounting, law) |
|---|---|---|
| Below $201,750 single / $403,500 joint | Full 20% deduction. Set salary at the defensible reasonable-compensation floor. | Full 20% deduction. Same strategy: defensible floor. |
| Inside the phase-in range | Wage limit phases in. Model several salary levels; the best point is usually above the floor. | Deduction phases down toward zero. Model whether lowering taxable income (e.g. retirement contributions) keeps you in range. |
| Above $276,750 single / $553,500 joint | Wage limit fully applies. Target about 2/7 of pre-salary profit, but never below reasonable compensation. | No QBI deduction. Set salary on reasonable compensation and retirement goals alone. |
Section 5: payroll cadence, Solo 401(k) and keeping money flows separate
The December true-up problem
Some owners take distributions all year and run one large paycheck in December. That paycheck isn’t late, because payroll taxes are due when wages are paid. The risk is what it says about the rest of the year: you were working every month, but every payment you took before December was labeled a distribution.
Compliance trap: If the IRS treats those earlier draws as disguised wages, the corporation owed payroll taxes in the quarters when it paid them. That brings back the §6656 failure-to-deposit penalties and interest for those quarters, plus corrected Forms 941. A one-time payroll also makes it easy to miss the health-insurance W-2 entries and your retirement deferral elections.
The fix is simple: run payroll on a fixed schedule (monthly is common for solo owners), so salary is paid as you earn it and distributions come out of profit afterward.
How your salary sets your retirement contributions
In a Solo 401(k), the employer profit-sharing contribution is limited to 25% of your W-2 compensation from the S corporation. Distributions don’t count. For 2026, employee deferrals are capped at $24,500 (plus catch-up contributions if you’re 50 or older), and total annual additions at $72,000.
| W-2 salary | Max employer contribution (25%) | Employee deferral (2026) | Total before catch-up |
|---|---|---|---|
| $30,000 | $7,500 | $22,500 (limited by pay) | $30,000 |
| $60,000 | $15,000 | $24,500 | $39,500 |
| $90,000 | $22,500 | $24,500 | $47,000 |
| $190,000 | $47,500 | $24,500 | $72,000 (annual limit) |
At a $30,000 salary, you can’t defer the full $24,500 and still have take-home pay to cover payroll taxes, so the deferral in that row is reduced. A depressed salary saves FICA today but caps tax-deferred savings for the year. A SEP-IRA has the same 25%-of-W-2 limit without the employee deferral, so a low salary hurts it even more.
Four separate money flows
Keep each type of payment on its own track, with its own records:
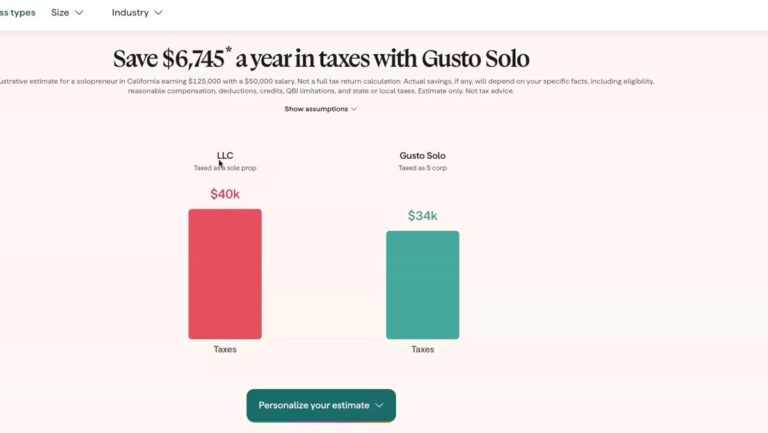
- W-2 payroll: your salary, run on a fixed schedule through a payroll provider that makes the tax deposits and files Forms 941, 940 and W-2 for you. We use Gusto (see our Gusto review with real pricing); its Gusto Solo plan is built for one-owner S corps.
- Accountable plan reimbursements: a monthly transfer that matches an approved expense report.
- Health insurance: premiums paid directly by the company or reimbursed to you, and added to your W-2 through payroll.
- Distributions: transfers from profit after payroll and reimbursements, labeled as distributions in your books.
Why it matters: When a revenue agent asks what a $12,000 transfer was, you want to answer with one document (a pay stub, an expense report, an insurance invoice or a distribution entry), not a reconstruction.
Compare what payroll providers cost for a one-person company with our payroll cost calculator. Set the slider to 1.
Year-round implementation checklist
- January: set the salary. Update your reasonable-compensation study with current OEWS data, model the QBI and retirement effects, and record the salary in a written member consent or board resolution.
- January: set up payroll. Run payroll at least monthly through a full-service provider that makes the tax deposits and files Forms 941, 940 and W-2.
- Before the first reimbursement: adopt the accountable plan. Get it in writing, then submit expense reports within 60 days and return any excess within 120 days.
- Every month: keep the money flows separate. Pay salary, reimbursements, insurance and distributions as distinct, documented transfers.
- Before the last payroll of the year: health insurance and retirement. Add the year’s 2% shareholder premiums to your W-2 (Box 1 only), and confirm Solo 401(k) deferrals have gone through payroll.
- Year-end: review. Compare salary to distributions against your study, true up any shortfall through regular payroll going forward, and keep the file with your tax records.
The bottom line
Paying yourself as little as possible isn’t the goal. The goal is a salary that’s defensible on the facts, paid on a regular schedule, and set where payroll tax, the QBI deduction and your retirement contributions balance out, with records that show your work. That’s what makes the S-corp savings hold up if the IRS ever looks.
FAQs
Is there a safe salary-to-distribution ratio for S corporations?
No. No statute, regulation or court decision sets a percentage. Reasonable compensation depends on your skills, duties, hours, comparable market pay and the business’s results, as listed in IRS Fact Sheet 2008-25.
Can I take a $0 salary if my S corporation had a bad year?
If the business has no profit to distribute and you take no distributions, a low or zero salary is easier to justify. The risk comes from taking distributions while paying yourself little or nothing for services you clearly performed, as in Radtke and Spicer.
Why didn’t I get the self-employed health insurance deduction?
The most common reason is that your W-2 showed the premiums in Box 1 but your Box 5 Medicare wages were too low or zero. The deduction is limited to your S-corp wages under §162(l)(5), so it needs a real salary to work.
Does my S-corp salary affect my QBI deduction?
Yes. Your salary reduces the business’s QBI. Below the 2026 thresholds ($201,750 single, $403,500 joint), a lower defensible salary means a larger deduction. Above them, a non-service business needs W-2 wages to qualify, and service businesses lose the deduction entirely above the end of the phase-in range.
How often should a single-owner S corporation run payroll?
Monthly is common and easy to defend. What matters is regularity: salary paid as you earn it, rather than one large December paycheck after a year of distributions.
Figures reflect 2026 IRS limits, Rev. Proc. 2025-32, and the One Big Beautiful Bill Act. Example salaries and wage data are illustrative. This article is general information, not tax or legal advice for your situation. Have a CPA or tax attorney review your salary study and plan documents before you rely on them. This post contains our Gusto referral link; if you sign up through it, we may receive a reward at no cost to you.
Keep reading
Reviews
Gusto Review 2026: What We Actually Pay (Real Account Walkthrough)
A walkthrough of our real Gusto account: what we pay on the Simple plan ($49 + $6 per person), Gusto Solo for S-corp owners, the taxes and compliance dashboard, and how Gusto's price compares with 10 other payroll providers.
October 23, 2026
Industry guides
Best Payroll Software for Food Trucks and Mobile Concessions (2026)
The best payroll for food trucks, concession trailers and caterers: tip handling, seasonal staff, events in other states, and the new 2026 W-2 tip reporting rules.
October 22, 2026
Head-to-head
Gusto vs QuickBooks Payroll: Real Cost Comparison for 1–50 Employees (2026)
Gusto vs QuickBooks Payroll pricing side by side at 1, 5, 10, 25 and 50 employees — including the multi-state surcharge that flips which one is cheaper.
October 22, 2026